Nomination is one of the most important aspects of a life insurance policy. While buying life insurance, people generally focus on the sum assured, premium, policy term and benefits. However, choosing and regularly updating the right nominee is equally important.
A nominee is the person designated by the policyholder to receive the policy money in the event of the death of the life assured, subject to the applicable law and policy terms. In India, Section 39 of the Insurance Act, 1938 provides the statutory framework relating to nomination in life insurance policies.
Let’s understand what Nomination means, who can be a nominee, what a beneficiary nominee is, and why keeping nomination details updated is important.
Table of Contents
What is Nomination in Life Insurance?
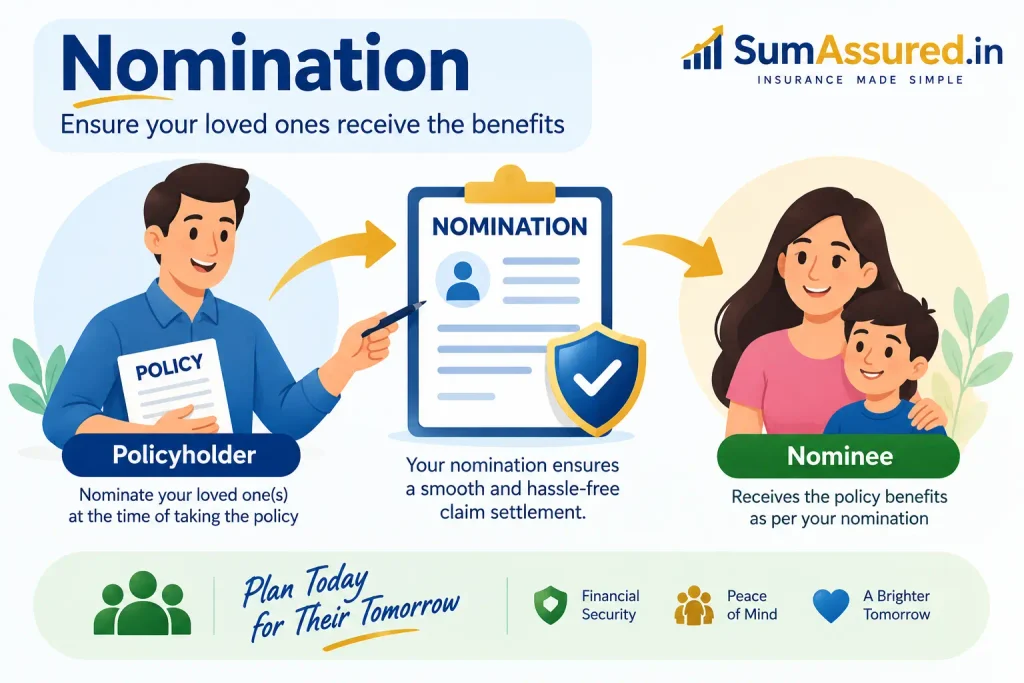
Nomination is the process by which a policyholder names one or more persons who can receive the policy proceeds after the death of the life assured.
For example, if Rahul purchases a life insurance policy with a sum assured of ₹50 lakh and nominates his wife, the insurer will process the death claim according to the policy conditions and applicable law and pay the amount to the eligible nominee.
Nomination can generally be made when purchasing the policy or subsequently, before the policy matures for payment, following the insurer’s prescribed process. Section 39 specifically permits the policyholder to nominate one or more persons.
Who Can Be a Nominee?
A policyholder may nominate eligible persons according to the applicable rules and insurer’s procedures. Common nominees include:
- Spouse
- Children
- Parents
- Other persons permitted under applicable provisions
The policyholder should provide accurate details such as the nominee’s name, relationship, date of birth and address wherever required.
If there is more than one nominee, the policyholder should carefully provide the required details and applicable share information as prescribed.
What is a Beneficiary Nominee?
The term beneficiary nominee is important when discussing life insurance nomination.
Under Section 39(7) of the Insurance Act, 1938, where a policyholder nominates their parents, spouse, children, spouse and children, or any of them, the nominee or nominees are described as being beneficially entitled to the amount payable by the insurer, subject to the provisions of the section.
In simple terms, certain close family members nominated under the statutory provision can have a beneficial entitlement to the insurance proceeds, rather than merely being the person who receives the money from the insurer.
This distinction is important because nominee, beneficial nominee and legal heir are not necessarily interchangeable terms.
Nominee vs Beneficiary Nominee vs Legal Heir
These terms are often confused.
A nominee is the person named by the policyholder under the insurance policy to receive the policy proceeds following the death of the life assured.
A beneficiary nominee, in the context of Section 39(7), refers to specified family nominees—such as a spouse, children or parents—who are beneficially entitled to the amount payable, subject to the statutory provisions.
A legal heir, on the other hand, is a person who has rights in the deceased person’s estate under the applicable succession law.
Therefore, policyholders should not assume that every nominee has exactly the same legal position. The nature of the nomination, the relationship of the nominee, the policy structure and applicable law can all be relevant.
Can a Minor Be a Nominee?
Yes, a minor can be nominated subject to the applicable requirements.
Where the nominee is a minor, Section 39 permits the policyholder to appoint a person, in the manner prescribed by the insurer, to receive the policy money if the death of the life assured occurs while the nominee is a minor.
Therefore, parents who nominate minor children should ensure that the required appointee details are correctly recorded and kept updated.
Can You Change the Nomination?
Yes. A policyholder should review and update the nomination whenever there is a significant change in family circumstances.
For example, nomination should be reviewed after:
- Marriage
- Birth of a child
- Death of an existing nominee
- Divorce or significant change in family circumstances
- Changes in financial or estate-planning arrangements
Keeping outdated nominee information can create avoidable complications during the claim process.
What Happens if the Nominee Dies?
If a nominee dies before the life assured, the policyholder should review the nomination and make a fresh nomination wherever applicable.
Section 39 also contains provisions for situations where a nominee survives the life assured but dies before the policy proceeds are paid. In certain cases covered by the beneficial-nomination provisions, the relevant amount may become payable to the heirs or legal representatives of that nominee, subject to the statutory conditions.
Why is Nomination Important?
Proper Nomination serves several important purposes:
1. Helps Identify the Intended Recipient
Nomination provides the insurer with the policyholder’s recorded designation of the person or persons intended to receive the policy proceeds.
2. Helps the Claim Process
Having updated nominee information can make the claim documentation and communication process more organised.
3. Supports Family Financial Planning
Life insurance is purchased primarily to provide financial protection. Keeping nominee details updated is therefore an important part of maintaining the policy.
4. Helps Avoid Outdated Information
Family circumstances change over time. Reviewing nomination periodically ensures that policy records remain aligned with the policyholder’s current circumstances.
Important Points to Remember
Policyholders should:
- Check whether their policy has a valid nomination.
- Provide accurate nominee details.
- Update nomination after major family changes.
- Review the nomination if the existing nominee dies.
- Provide appointee details where a minor is nominated.
- Keep a record of policy numbers and nominee information.
- Inform family members about the existence of the life insurance policy.
- Refer to the insurer’s policy documents and applicable regulations for the exact procedure.
Final Thoughts
Nomination in a life insurance policy is a simple but important part of financial planning. It identifies the person or persons designated to receive the policy proceeds after the death of the life assured, subject to the policy terms and applicable law.
The concept of a beneficiary nominee is particularly important because Section 39 of the Insurance Act provides beneficial entitlement in specified circumstances for nominees such as parents, spouse and children.
Therefore, don’t simply purchase a life insurance policy and forget about its nomination. Review your Nomination whenever your family circumstances change and make sure the information recorded with your insurer is accurate and up to date.
2 thoughts on “Nomination in Life Insurance: Beneficiary Nominee, Rules and Importance”